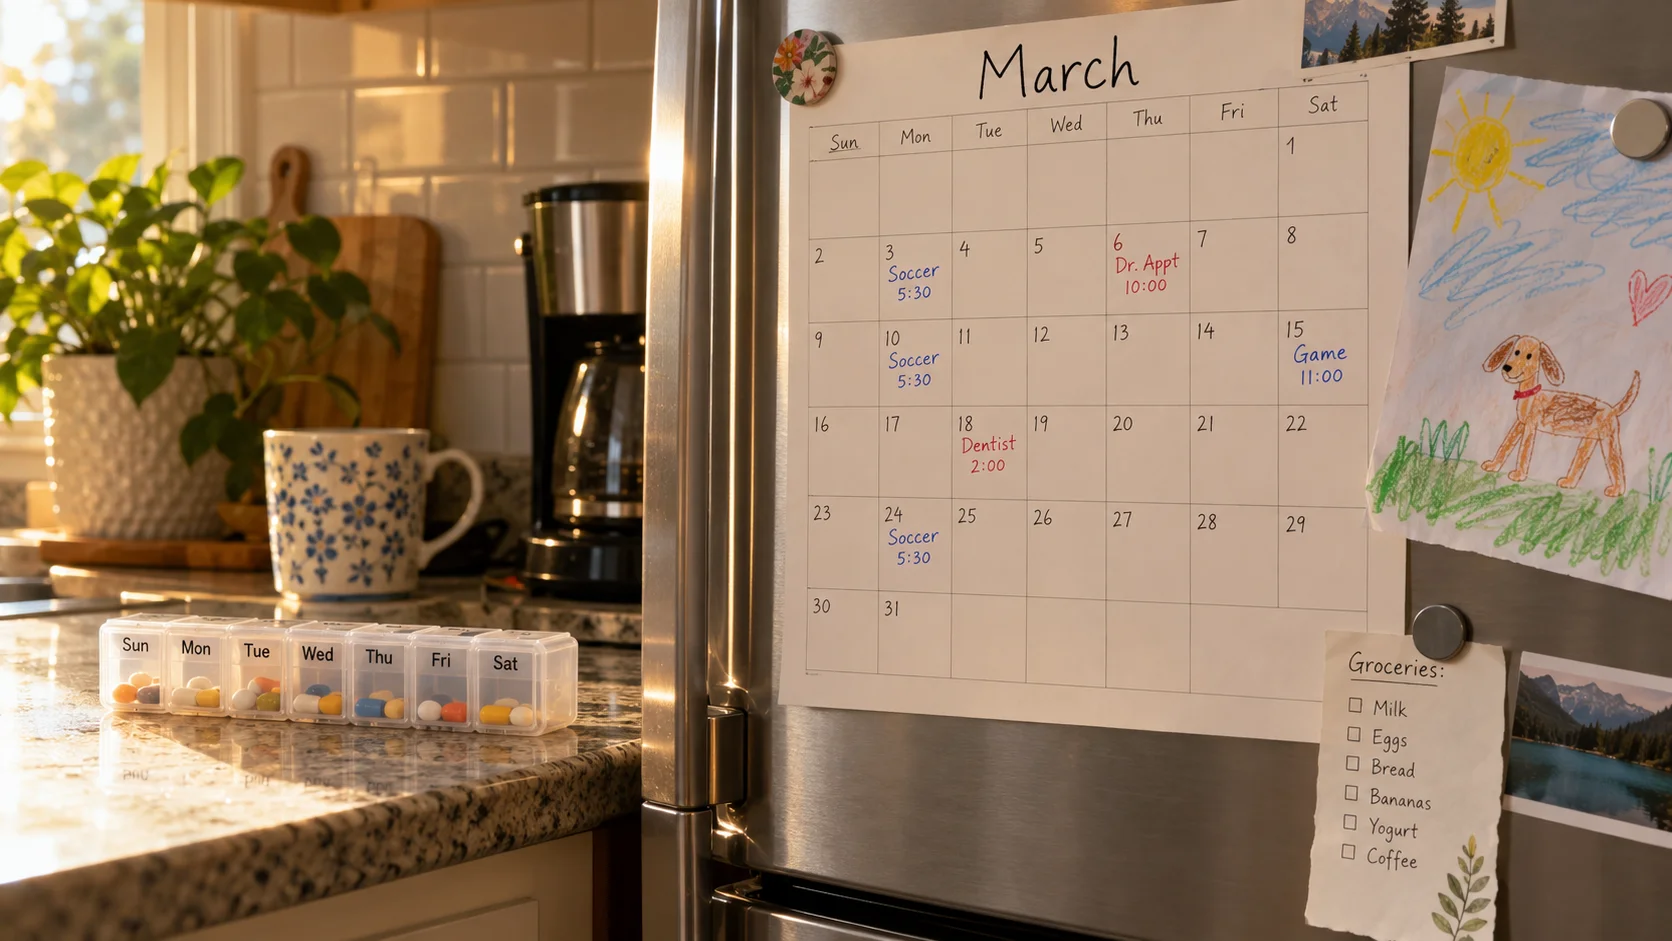
The calendar on the refrigerator tells the story before anyone explains it. Soccer practice on Tuesday, a parent-teacher conference on Wednesday, and, written in a different color, a cardiology follow-up for a mother who no longer drives at night, all arranged by someone who is also expected at work by nine every morning.
That person has a name in the research, the sandwich generation, and it now describes a quarter of American adults. Pew Research Center reported in August that 54 percent of adults in their 40s have a parent 65 or older along with a child under 18 or an adult child they still support financially. The help built for this squeeze, from job-protected leave to local respite programs and tax rules for supporting a parent, goes unclaimed in many families simply because nobody told them it was there.
November is National Family Caregivers Month, observed through presidential proclamations since 1997 and led by the Caregiver Action Network, whose theme this year is "Care Connects Us." The days before it begins are a good time to take stock of what a family is carrying and what support it can call on.
How Many Families Are Carrying Both Generations
The scale has grown quickly. Pew's figures come from a September 2025 survey, and the center notes that when it last measured the sandwich generation in 2021, 23 percent of adults fit the definition, against a quarter now.
The caregiving side of the picture comes from Caregiving in the US 2025, the report from AARP and the National Alliance for Caregiving. It counts 63 million Americans, nearly 1 in 4 adults, providing ongoing care, an increase of 20 million since 2015, and AARP's research summary finds that 29 percent of them are sandwich generation caregivers supporting both children and adults.
"The data reveals a portrait of ordinary Americans providing extraordinary care," said Jason Resendez, president and chief executive of the National Alliance for Caregiving.
The cost lands on household budgets. According to the report's release, nearly half of caregivers experienced at least one major financial impact, AARP chief executive Myechia Minter-Jordan cited roughly $7,200 a year in out-of-pocket spending, and the research summary adds that a quarter of caregivers are taking on debt and one in five cannot afford basic needs like food. Six in 10 family caregivers also hold jobs, which is why workplace leave is the first place to look.
Leave From Work: What the Law Protects
The federal floor
The Family and Medical Leave Act allows eligible employees to take up to 12 workweeks of leave in a year to care for a child, parent or spouse with a serious health condition, with their job protected while they are gone. Eligibility applies to private employers with 50 or more employees, and the worker must have been with the employer for at least 12 months, logged at least 1,250 hours of service and work at a location with at least 50 employees within 75 miles.
One limit catches many couples by surprise. The Labor Department's definition of a parent covers biological, adoptive, step and foster parents, but it states plainly that the term does not include parents-in-law, so a spouse caring for a mother-in-law cannot rely on FMLA protection alone.
State paid leave can go further
State paid leave programs can fill that in-law gap. New York's program covers care for a parent, stepparent, parent-in-law and grandparent, and in 2026 it pays 67 percent of a worker's average weekly wage up to a maximum weekly benefit of $1,228.53, for up to 12 weeks. Employees fund it through a payroll contribution of 0.432 percent, capped at $411.91 for the year, so most New York workers are already paying for coverage they may not know they have.
Families outside New York should check their own state's labor or paid leave agency, since eligibility rules, benefit amounts and the list of covered relatives vary widely from one program to the next.
Respite and Local Services Most Families Never Call
The federal government has funded caregiver support since 2000 through the National Family Caregiver Support Program, authorized under Title IIIE of the Older Americans Act. Its grants pay for five kinds of help: information about available services, assistance gaining access to them, individual counseling and support groups and caregiver training, respite care, and limited supplemental services, for adult family members and other informal caregivers looking after people 60 and older.
The front door to those services is the Eldercare Locator, run by the Administration for Community Living, which links callers to their state and local Area Agencies on Aging. It can be reached toll-free at 1-800-677-1116 from 8 a.m. to 9 p.m. Eastern, Monday through Friday, or online at eldercare.acl.gov. HHS announced plans in 2025 to reorganize the Administration for Community Living, so families should confirm current program details with their local agency.
Respite care is often the most valuable item on that list, since a few hours of adult day programming or in-home help each week can be what keeps a caregiver working. Parents who already feel stretched thin will recognize the warning signs we covered in our reporting on parental burnout, and those signs tend to sharpen once an aging parent's needs are added to a child's.
The Tax Rules for Supporting a Parent
Supporting a parent can change a family's tax return. For the 2025 tax year, which covers the returns families file this coming spring, IRS Publication 501 says a parent can be a qualifying relative if their gross income for the year was less than $5,200 and the taxpayer provided more than half of their total support. A qualifying parent can make the family eligible for the $500 credit for other dependents, which begins to phase out above $200,000 of adjusted gross income, or $400,000 for married couples filing jointly.
The same rules can affect filing status. Publication 501 notes that for head of household purposes a dependent parent does not have to live with you, which matters for a single parent paying for a mother's apartment or assisted living.
When a parent who cannot care for themselves lives in the home for more than half the year, the child and dependent care credit can apply to the cost of adult day care or in-home help that lets the caregiver work. For 2025, Publication 503 caps eligible expenses at $3,000 for one qualifying person or $6,000 for two or more, with a credit of up to 35 percent. The 2025 federal tax law reshaped that credit and the dependent care FSA starting in 2026, and our breakdown of the $7,500 dependent care FSA versus the credit walks through the new math for anyone enrolling in benefits this fall.
Sharing the Load Inside the Family
Leave and services cover only part of the work. The rest is coordination, and families with siblings often divide it by what each person can realistically offer: the sibling who lives nearest handles appointments, the one with the most flexible job manages calls with insurers and pharmacies, and the one with more income contributes to paid help or a monthly respite day.
Writing that arrangement down keeps it from turning into resentment. A short monthly call with a shared document listing medications, doctors, account logins and who covers which week can do a great deal of that work, and the format matters less than the habit of meeting.
Children belong in the conversation too, in age-appropriate ways. A ten-year-old who knows why a grandparent's visits now come with a cane and a pill organizer is less likely to feel that a parent's divided attention is about them, and teenagers can take on real tasks, such as a weekly phone call or help with groceries, that build a bond between generations.
For the person at the center of the refrigerator calendar, the first call is usually the hardest one to make. The Eldercare Locator line, 1-800-677-1116, opens at 8 a.m. Eastern on Monday, October 26, a week before National Family Caregivers Month begins.